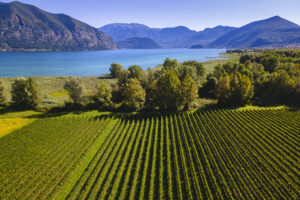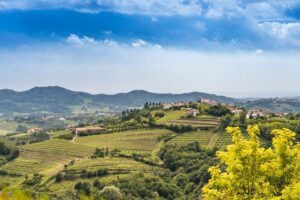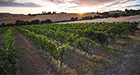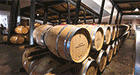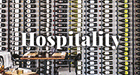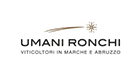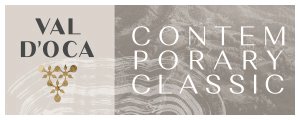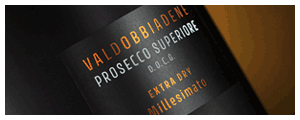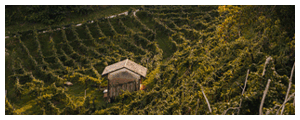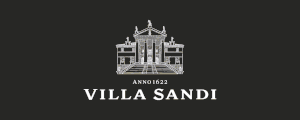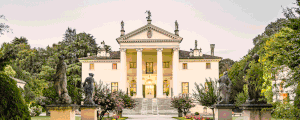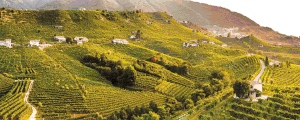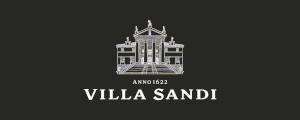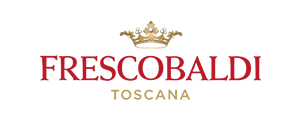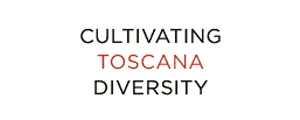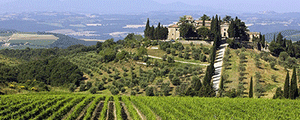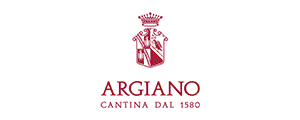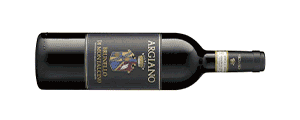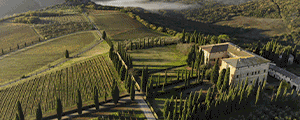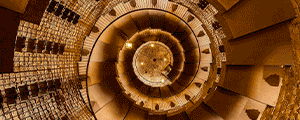
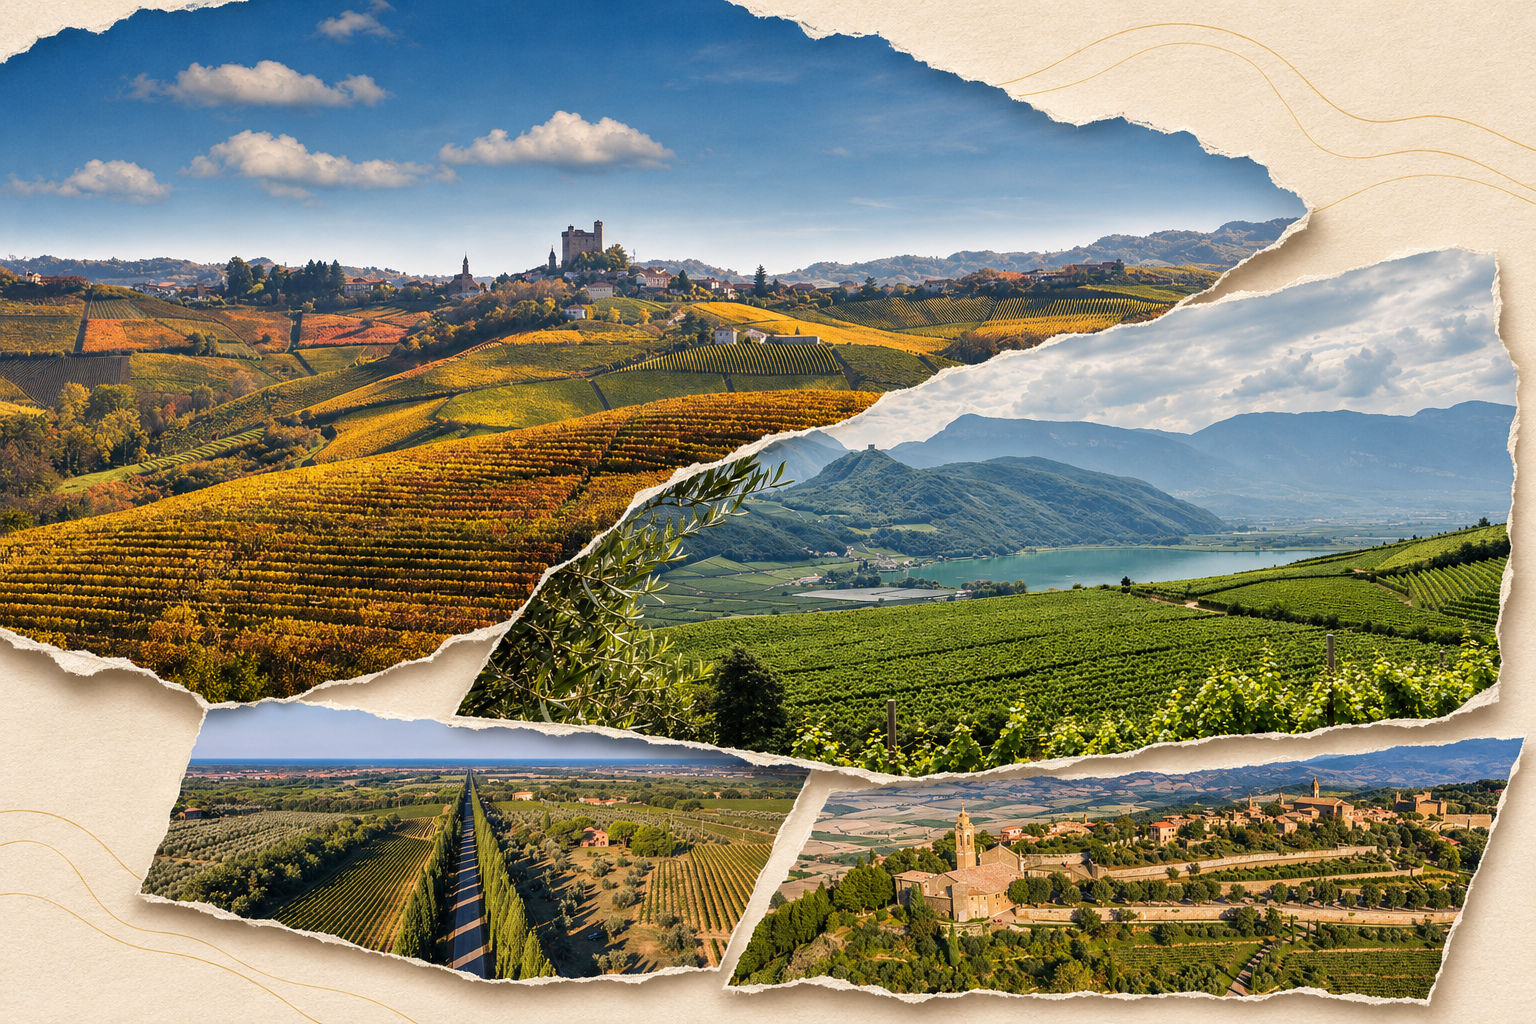
Although the wine market has been facing more than a few challenges for some time, land values, at least in the most important denominations and wine regions, appear to be holding firm, at least at their upper end. This is according to preliminary findings from the Annual Survey of the Italian Land Market, carried out by Crea through its Center for Policies and Bioeconomy, with the support of Conaf, for 2025. According to the report, in 2025 “the agricultural land sales market regained momentum, albeit at different speeds across the country. Average land values rose by 0.9%, with the national average approaching 23,000 euros per hectare and a marked territorial gap, ranging from 48,900 euros per hectare in North-Eastern Italy to 8,600 euros in the Islands. The most valuable land is generally located in lowland areas, with some notable exceptions linked to specialized production”. Winegrowing areas are among those exceptions. At the very top of the ranking, according to data reviewed by WineNews, are still the vineyards in Barolo Docg area of the Lower Langhe around Alba, where maximum values are estimated at 2.3 million euros per hectare, starting from a minimum of 350,000 euros per hectare. They are followed by South Tyrol Doc vineyards in the Lake Caldaro (Kaltern) area, with peak values reaching 1.1 million euros per hectare (starting from 600,000 euros per hectare, the highest “minimum” value recorded among vineyard areas). Sharing third place, with maximum values of 1 million euros per hectare, are Bolgheri Doc vineyards (starting from 300,000 euros per hectare) and Brunello di Montalcino Docg vineyards (starting from 250,000 euros per hectare). These vineyards are also among the most valuable agricultural lands overall in Italy. The national “top ten” across all agricultural sectors includes the apple orchards of Val Venosta (430,000-720,000 euros per hectare) and the Adige Valley (380,000-570,000 euros per hectare), the Valdobbiadene vineyards dedicated to Prosecco Docg (300,000-550,000 euros per hectare), as well as the Doc vineyards of Lower Val Venosta and the Isarco Valley near Bressanone, both valued between 300,000 and 500,000 euros per hectare. Also included are irrigated horticultural and floricultural lands in the Albenga Plain in Liguria, valued between 280,000 and 500,000 euros per hectare.
Looking more broadly at vineyards, which in many cases command values well above the national average for farmland, prices range from 230,000 to 450,000 euros per hectare for vineyards north of Trento, largely dedicated to Trentodoc production, and from 300,000 to 400,000 euros per hectare for the Asolo Hills Docg vineyards, also largely devoted to Prosecco production. Values range between 150,000 and 300,000 euros per hectare for the Saint-Christophe Doc vineyards in the Aosta Valley and for the Collina Bresciana Doc vineyards in Lombardy. Elsewhere, a hectare of Chianti Classico Docg vineyard in the Florence area is valued between 90,000 and 210,000 euros, while on the Siena side values are lower, ranging from 90,000 to 150,000 euros per hectare. The Bergamo Hills Doc vineyards are worth between 120,000 and 200,000 euros per hectare, the Valtellina Doc vineyards between 105,000 and 171,000 euros, the lowland vineyards of the Lower Piave area between 65,000 and 150,000 euros, and the Collio Doc vineyards, home to some of Friuli-Venezia Giulia finest white wines, between 60,000 and 140,000 euros per hectare.
More generally, the report highlights that “supply and demand remain broadly balanced, with demand holding a slight edge and the number of transactions remaining stable. Purchases are driven mainly by farmers, while sellers are predominantly those exiting agricultural activity and owners of inherited land who have no intention of cultivating it. Farmers’ decisions are also being influenced by the 2023-2027 CAP measures and by growing demand for land suitable for renewable energy installations”.
According to Crea, the rental market remains stable, although demand is becoming increasingly selective. “Rental rates have remained largely unchanged, except in the most productive areas where increases have been recorded. Demand is concentrated on irrigated, consolidated, accessible and mechanisable land, as well as on areas dedicated to specialized crops. This demand is mainly supported by well-structured farming businesses, livestock operators and agricultural contractors, while marginal land is finding it increasingly difficult to attract tenants. On the supply side, the closure of smaller farms and the lack of generational renewal continue to weigh on the market. Regional dynamics also differ significantly: in Northern Italy demand is stronger in irrigated plains and livestock districts, while in Southern Italy the market is less dynamic and supply is more abundant in inland areas”.
Looking ahead, “market operators do not expect major changes in the balance of the land market overall. However, more than 40% anticipate an increase in the amount of land available, primarily as a result of farm closures in marginal areas. As for rentals, substantial continuity is expected, with demand becoming increasingly more concentrated on land offering the highest productive potential.
Copyright © 2000/2026
Contatti: info@winenews.it
Seguici anche su Twitter: @WineNewsIt
Seguici anche su Facebook: @winenewsit
Questo articolo è tratto dall'archivio di WineNews - Tutti i diritti riservati - Copyright © 2000/2026